

Small and medium-sized businesses in the United States increasingly need faster and more flexible access to capital. Traditional business loans can involve lengthy applications, extensive documentation, strict eligibility requirements, and longer approval timelines. This has created an opportunity for digital lending models to offer businesses alternative ways to access financing.
P2P Lending Platforms are becoming an important part of this changing financial ecosystem. By digitally connecting borrowers with individual or institutional investors, these platforms can simplify the lending process, automate decision-making, and provide a more technology-driven approach to business financing.
What Are P2P Lending Platforms?
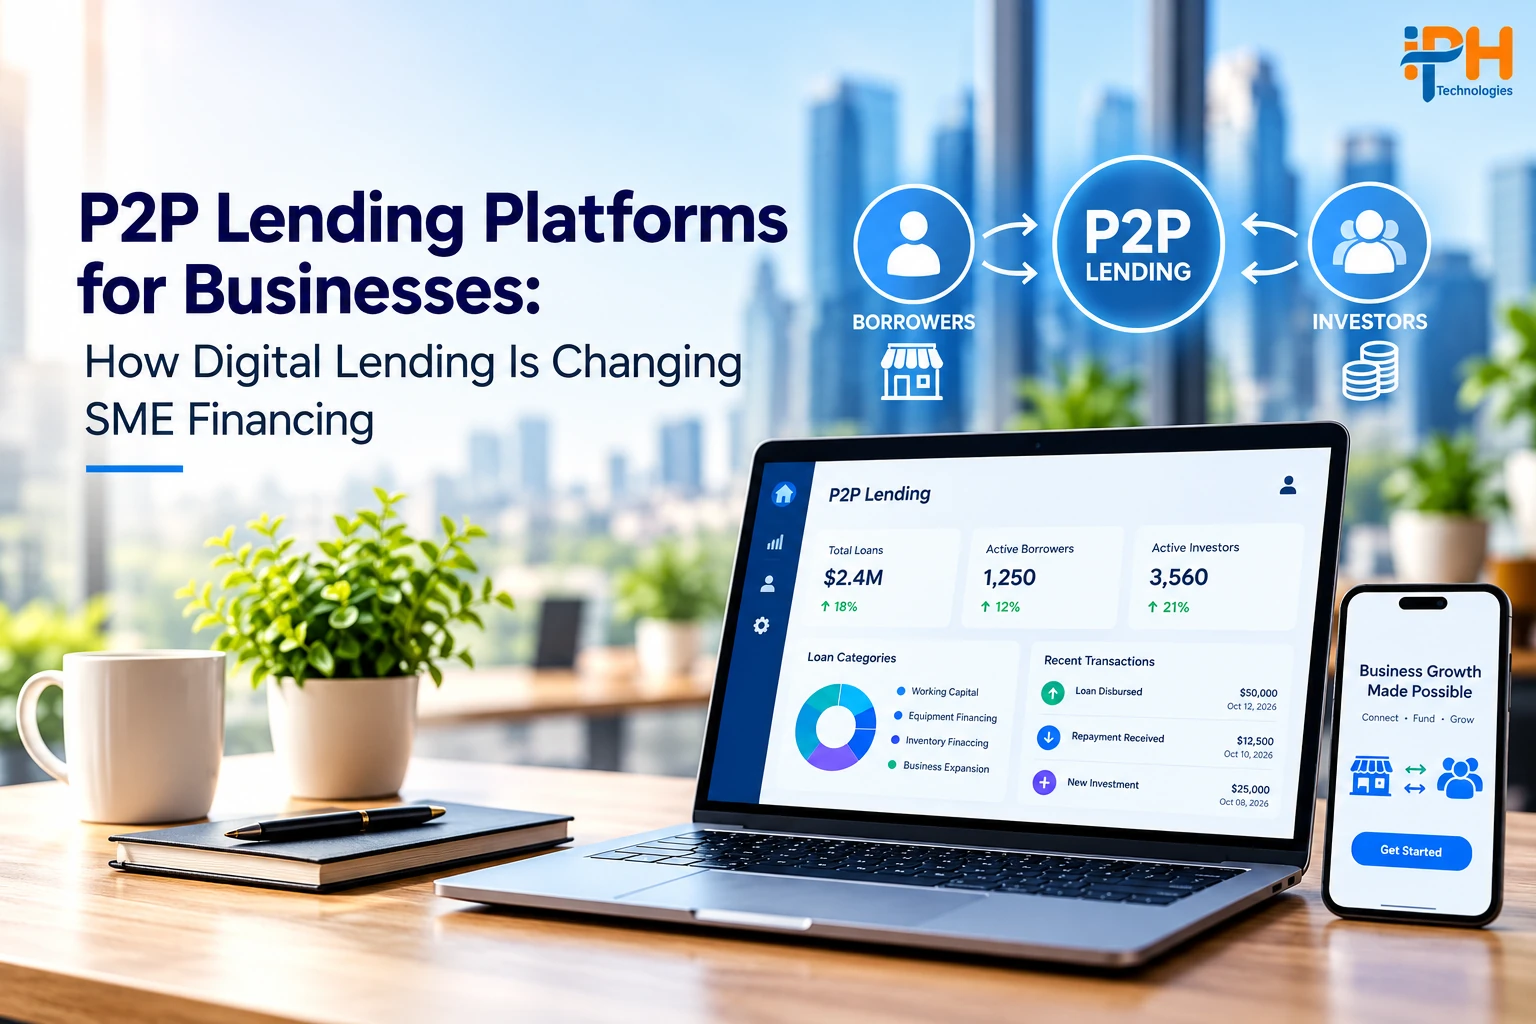
P2P lending platforms, or peer-to-peer lending platforms, are digital marketplaces that connect borrowers seeking financing with investors willing to provide capital.
Instead of relying entirely on traditional banking infrastructure, a P2P platform can manage much of the lending journey digitally. Businesses can submit applications, provide financial information, complete identity verification, receive lending offers, and manage repayments through an online platform.
For U.S. businesses, these platforms can support different financing requirements, including working capital, business expansion, equipment purchases, inventory financing, and other operational needs.
Why P2P Lending Is Becoming Important for U.S. SMEs
Access to financing can be a major challenge for small and medium-sized businesses. A business may have consistent revenue and growth potential but still face difficulties obtaining traditional financing because of credit history, documentation requirements, collateral requirements, or lengthy approval processes.
Digital lending platforms can address some of these challenges by using technology to streamline the lending workflow.
How P2P Lending Platforms Are Changing SME Financing
1 Faster Digital Loan Applications
Traditional lending can require multiple forms, documents, meetings, and manual reviews. Digital P2P lending platforms can bring these steps into a single online experience.
Businesses can submit applications digitally and provide relevant financial information through secure integrations. Automated workflows can then route applications to the appropriate underwriting or approval process.
This creates a faster and more convenient experience for businesses looking for financing.
2 Data-Driven Credit Assessment
Modern lending platforms can use multiple data sources to evaluate borrower risk.
Depending on the platform’s business model and applicable regulations, data may include credit history, business revenue, transaction information, cash flow, repayment history, and other financial indicators.
AI and machine learning can further help lenders identify patterns in financial data and support more consistent risk assessment.
3 Automated Loan Matching
One of the important capabilities of P2P lending platforms is connecting suitable borrowers with potential investors.
A platform can use predefined criteria, risk categories, investment preferences, loan requirements, and other parameters to support loan matching.
Automation can reduce manual intervention while helping investors discover opportunities that align with their investment preferences.
4 Digital Investor Management
A successful P2P lending platform needs to serve both sides of the marketplace.
Investors may need dashboards to monitor funded loans, expected returns, repayment activity, portfolio distribution, and other relevant information.
A centralized investor dashboard can provide greater visibility and make portfolio management easier.
5 Automated Repayment Management
Once a loan is funded, the platform needs to manage repayment schedules and transaction workflows.
Features such as automated payment reminders, recurring payments, transaction tracking, repayment history, and notifications can simplify loan servicing.
Automation can also help platform operators monitor repayment activity and identify accounts that may require additional attention.
Key Features of a Modern P2P Lending Platform
Businesses planning to launch a digital lending marketplace should consider features for borrowers, investors, administrators, and compliance teams with:
☑ Borrower Registration and Onboarding
A streamlined onboarding process can allow businesses to create accounts, submit business information, upload documentation, and complete required verification steps.
☑ Loan Application Management
Borrowers should be able to submit loan applications, track their application status, review available offers, and manage required documentation through a centralized dashboard.
☑ Credit and Risk Assessment
Risk assessment functionality can help evaluate borrower profiles using approved financial and credit data sources. AI-powered analytics can potentially support automated risk scoring and underwriting workflows.
☑ Investor Dashboard
Investors can use dashboards to review available opportunities, understand risk information, manage investments, and monitor repayment performance.
☑ Loan Marketplace
A marketplace interface can present eligible lending opportunities according to platform rules and applicable regulatory requirements.
☑ Payment and Repayment Integration
Payment infrastructure allows the platform to facilitate loan disbursements and repayments while maintaining transaction records.
☑ Notifications and Alerts
Email, SMS, and in-app notifications can keep borrowers and investors informed about applications, approvals, payments, repayment dates, and account activity.
☑ Admin and Compliance Dashboard
Administrators need tools to manage users, loans, transactions, verification workflows, risk parameters, disputes, reporting, and platform activity.
The Role of AI in P2P Lending Platforms
Artificial intelligence is becoming an important technology consideration for fintech platforms.
AI can support several areas of a P2P lending platform, including financial data analysis, risk assessment, fraud detection, customer support, document processing, and workflow automation.
For example, AI-powered document processing can help extract relevant information from uploaded financial documents. Machine learning models can assist with identifying patterns in borrower data, while AI-based fraud detection systems can flag unusual activity for further review.
P2P Lending Platforms vs Traditional Business Lending
The primary difference is the technology and financing model.
| Traditional Business Lending | P2P Lending Platforms |
|---|---|
| Traditional lending generally involves a financial institution acting as the lender. | A P2P model operates as a technology-enabled marketplace that facilitates connections between borrowers and investors, although actual structures vary considerably by platform. |
Security and Compliance Considerations for U.S. P2P Lending Platforms
Security and regulatory compliance are critical when developing a financial technology platform for the U.S. market.
A P2P lending platform may handle sensitive financial, identity, and business information. Developers therefore need to design the platform with security controls from the beginning.
Depending on the platform’s structure, target users, lending model, and jurisdictions, relevant considerations may include:
How Businesses Can Benefit From Digital P2P Lending
For SMEs, digital lending can offer several potential advantages.
| # | Benefit | How it helps |
|---|---|---|
| 1 | Convenient Access | Businesses can apply for financing through an online platform without relying entirely on branch-based processes. |
| 2 | Faster Workflows | Automated verification, underwriting support, and document processing can reduce unnecessary manual steps. |
| 3 | Alternative Financing | P2P lending can provide another financing channel alongside banks, credit unions, and other financial institutions. |
| 4 | Digital Transparency | Borrowers and investors can access application, loan, payment, and portfolio information through centralized dashboards. |
| 5 | Technology-Driven Operations | Automated workflows can help lending businesses manage larger volumes without increasing manual processes at the same rate. |
What Fintech Companies Need to Consider Before Building a P2P Lending Platform
Developing a P2P lending platform requires more than creating borrower and investor dashboards.
The platform should also be designed for scalability. As transaction volume and user numbers increase, the architecture needs to support additional borrowers, investors, financial integrations, data processing, and reporting requirements without compromising performance or security.
API integrations are another important consideration. Depending on the business model, a platform may need integrations for identity verification, credit data, banking information, payments, accounting, fraud detection, notifications, and analytics.
Why Choose IPH Technologies for P2P Lending Platform Development?
Building a secure and scalable digital lending platform requires expertise across fintech, mobile application development, web development, APIs, cloud infrastructure, data security, and modern automation technologies.
IPH Technologies is an app and software development agency that helps businesses develop customized digital solutions using modern technologies.
For fintech businesses exploring P2P lending platform development, IPH Technologies can support the development of borrower and investor applications, admin dashboards, APIs, payment integrations, automated workflows, and AI-powered functionality.
The development approach can be tailored around the client’s business model, target market, security requirements, and scalability goals.
From initial product planning and UI/UX design to application development, API integration, testing, deployment, and ongoing improvements, a specialized development team can help transform a P2P lending concept into a production-ready digital platform.
The Future of P2P Lending Platforms in the U.S.
The U.S. lending ecosystem is becoming increasingly digital. Businesses expect faster online experiences, investors want better portfolio visibility, and fintech companies are exploring AI and automation to improve financial workflows.
As these expectations continue to evolve, P2P lending platforms are likely to become increasingly sophisticated. AI-assisted underwriting, automated fraud detection, real-time financial data integrations, personalized lending experiences, and intelligent loan management can shape the next generation of digital lending platforms.
Final Thoughts on P2P Lending Platforms
P2P lending platforms are changing how businesses can access alternative financing by bringing borrowers, investors, data, automation, and financial services into a digital ecosystem.
For U.S. SMEs, this model can provide an additional financing channel alongside traditional lending. For fintech companies, it creates opportunities to develop innovative lending products powered by AI, automation, APIs, and modern financial technology.
However, success depends on more than technology. A successful P2P lending platform needs a clear business model, strong security, appropriate compliance planning, reliable financial integrations, effective risk management, and a scalable technology architecture.
With the right development partner, fintech companies can build secure, scalable, and user-focused P2P lending platforms designed to meet the evolving needs of the U.S. digital lending market.
Frequently Asked Questions (FAQs)
What are P2P lending platforms?
P2P lending platforms are digital marketplaces that connect borrowers with individual or institutional investors to facilitate loans.
How do P2P lending platforms help small businesses?
They can provide an alternative financing channel for working capital, inventory, equipment purchases, and business expansion.
Are P2P lending platforms suitable for U.S. businesses?
Yes, depending on the platform’s lending model, eligibility requirements, and applicable U.S. regulations, they can offer businesses an alternative to traditional financing.
What features should a P2P lending platform include?
Key features include borrower onboarding, loan applications, credit assessment, investor dashboards, payment integration, repayment tracking, and admin controls.
How does AI improve P2P lending platforms?
AI can support credit risk analysis, fraud detection, document processing, and workflow automation, subject to appropriate oversight and compliance.
How can IPH Technologies help develop a P2P lending platform?
IPH Technologies can help businesses develop customized lending applications with borrower and investor dashboards, API integrations, payment workflows, and AI-powered features.